Last updated:
Spending some time choosing a good-value home loan can save many thousands of dollars over time. A home loan is a long-term debt so even a small difference in cost adds up over time.
Home loan basics
Your home loan (mortgage) might be the biggest debt – for the longest period of time – that you ever have. Choosing a loan that’s right for you can save you thousands of dollars over time. The first step is to choose between a principal and interest (P&I) or an interest-only loan.
Principal and interest loans
Principal and interest will pay off the loan - most people get this type of home loan. You make regular repayments on the amount borrowed (the principal), plus you pay interest on that amount. You pay off the loan over an agreed period of time (loan term), for example, 30 years.
Interest-only loans
For an initial period (for example, five years), your repayments only cover interest on the amount borrowed. You aren't paying off the principal you borrowed, so your debt isn't reduced. Repayments may be lower during the interest-only period, but they will go up after that. Make sure you can afford them. See interest-only home loans.
Tip: choose the shortest loan term you can afford
Your loan term is how long you have to pay off the loan. It impacts the size of your mortgage repayments and how much interest you'll pay.
- A shorter loan term (for example, 25 years) means higher repayments, but you'll pay less in interest.
- A longer loan term (for example, 30 years) means lower repayments, but you'll pay more in interest.
You can use our mortgage calculator to work out what your repayments would be - and what the total cost of your home loan would be - depending on the interest rate and the length of the loan.
Compare interest rates
An interest rate even 0.2% lower could save you thousands of dollars over time. The Moneysmart mortgage calculator shows current average interest rates for both principal and interest and interest-only home loans, across both owner occupier and investment loans.
It’s important to weigh up the pros and cons of fixed and variable interest rates to decide which suits you.
A fixed interest rate stays the same for a set period, usually between one and five years. During that time, your repayments won't change, even if market interest rates rise or fall.
A variable interest rate can go up or down over time. Your lender decides whether to change the rate and by how much.
A partially-fixed rate (split loan) means a portion of your loan has a fixed rate and the rest has a variable rate. You can decide how to split the loan (for example, 50/50 or 20/80).
Check the average mortgage interest rate
Mortgage features may come at a cost
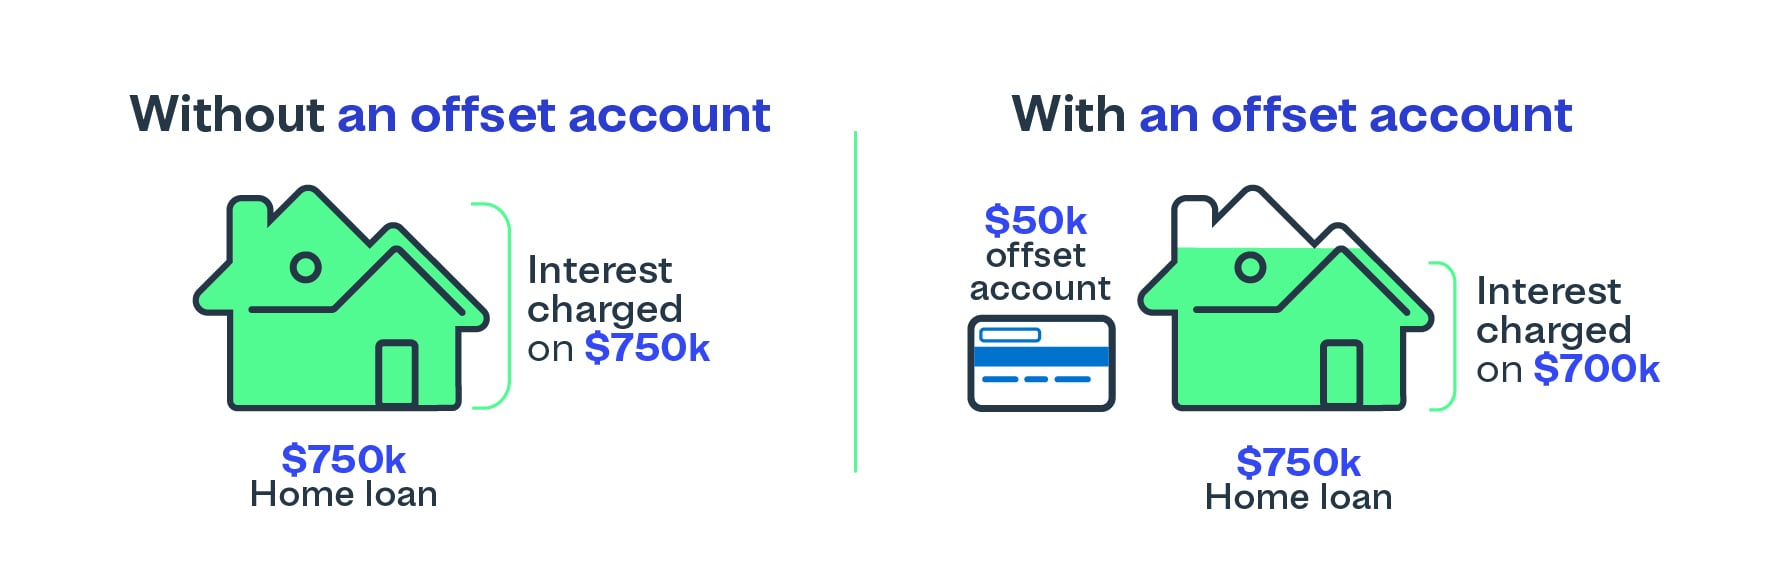
Home loans with more options or features can come at a higher cost. These could include an offset account, redraw or line of credit facilities. Most are ways of putting extra money into your loan to reduce the amount of interest you pay.
Weigh up if features are worth it
For example, suppose you are considering a $750,000 loan with an offset account. If you're able to keep $50,000 of savings in the offset, you'll pay interest on $700,000. But if your offset balance will always be low (for example under $10,000), it may not be worth paying for this feature.
Avoid paying more for 'nice-to-have' options
When comparing loans, consider your lifestyle and what options you really need. What features are 'must-haves'? What are 'nice-to-haves'? Is it worth paying extra for features you may never use? You may be better off choosing a basic loan with limited features.
Work out what you can afford to borrow
Be realistic about what you can afford. To give yourself some breathing room, calculate what your costs would be if interest rates went up by 3%.
Get the Key Fact Sheets
With the amount you can afford to borrow, compare loans from at least two different lenders. Check the loan interest rates, fees and features to get the best loan for you.
For all home loans you want to compare, get the Key Fact Sheet for that loan, based on the amount you're likely to borrow. You can generally get the Key Fact sheet from your mortgage broker (if you're using one), from the lender directly, or from the lender’s website.
The Key Fact Sheet is compulsory, and the layout is the same for every home loan across every lender. That way you can be confident that you're comparing like for like.
When you ask for the fact sheet, you’ll need to decide:
- repayment method – will you pay principal and interest or interest-only?
- repayment frequency – will you pay monthly, fortnightly, or some other frequency?
- type of interest rate – will you choose variable, or fixed, or a mix of both?
Once you’ve got the Key Fact Sheets for all the loans you're considering, compare these features:
|
Interest rate (per year) |
The interest rate you’ll be charged initially |
|
Peronalised comparison rate |
A single figure that combines the interest rate and most fees. This can help you compare the overall cost of different loans. |
|
Total amount to be paid back |
Shows how much you’ll repay over the life of the loan, including the amount borrowed and fees. |
|
Monthly repayment |
How much you'll have to pay each month on a loan |
|
Establishment fees |
Upfront fees charged when you take out the loan |
|
Ongoing fees |
Fees charged every month or year for administering a loan, also called service or administration fees |
Questions to ask that aren't covered by the Key Facts Sheet
The Key Facts Sheet is a great way to compare the cost of different loans, but it doesn't include every feature or condition. Before choosing a loan, ask the mortgage broker or lender:
- Can I make extra repayments without paying a fee?
- Is there an offset account or redraw facility?
- Are there fees for using loan features?
- Can I switch to a different loan later?
- Are there break costs if I repay the loan early or refinance?
- What happens when a fixed or introductory interest rate ends?
- Are there any other fees or charges that could apply?
Different lenders offer different features and conditions. Compare these alongside the cost information in the Key Facts Sheet to find the loan that's right for you.
With many lenders to choose from, you may decide to get a mortgage broker to find loan options for you. See using a mortgage broker for tips on what to ask your lender or broker.